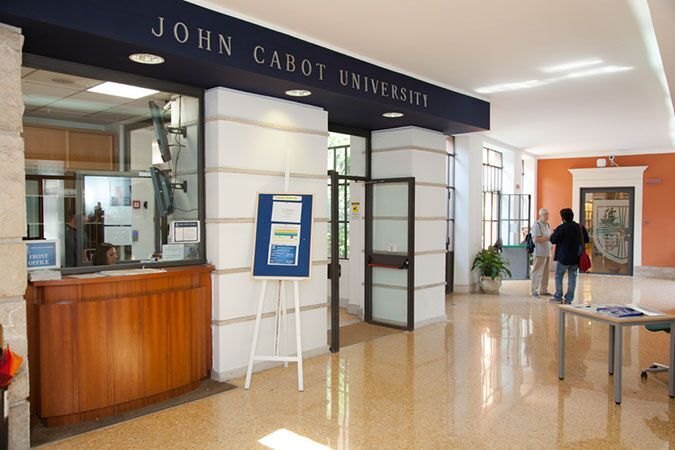
ROME, October 2 — The story begins with a quiet but consequential shift in how Europe engages with China, moving from efforts to reduce dependency toward negotiating the terms of a managed relationship. What unfolded at the ‘Securing Europe-China Policy: Emerging Trends’ roundtable on September 29 at John Cabot University’s Guarini Institute for Public Affairs revealed that October 2026 is the first real test of whether Beijing will accept European conditions.
At its heart, the EU now expects measurable changes in trade flows, market access, and the reliability of critical-material supplies, while Beijing views European measures as protectionism and attributes Europe’s competitiveness challenges to domestic factors. In 2025, EU goods exports to China fell 6.5% to €199.6 billion (approximately US$215.6 billion), while imports rose 6.4% to €559.4 billion (approximately US$604.2 billion), resulting in a trade deficit of €359.8 billion (approximately US$388.6 billion).
Brussels increasingly frames this imbalance as an industrial issue driven by weak Chinese domestic demand, large-scale industrial policy, and more sophisticated Chinese exports displacing European production domestically and in third markets. Since June, the two sides have negotiated the overall balance of the relationship through the China–EU Trade and Investment Consultations, launched in Brussels on June 29, which now cover trade and investment balancing, export controls, intellectual property, and WTO reform—replacing the previous approach of treating electric vehicles, procurement, rare earths, and subsidies as separate issues.
The dialogue is intended to be given time to deliver results, with failure potentially strengthening the case for autonomous European measures. Trade defence mechanisms are already active, including definitive anti-dumping duties of 4.3–45.3% imposed on Chinese tyres in July.
China accepts intensive consultation but rejects the legitimacy of European market restrictions as a response to the imbalance, citing WTO rules and emphasizing European competitiveness as the root cause. A key challenge lies in distinguishing strategic vulnerabilities from ordinary interdependence or competitive pressure that Europe may be over-securitising.
Member states remain divided: France favours a more defensive stance, Germany has hardened its position compared to a year ago—its deficit with China reached €89.3 billion (approximately US$96.5 billion) in 2025, and its exports continued to decline in the first half of 2026—while Italy and Spain are more supportive of action against sectors exposed to Chinese overcapacity.
The external context is also influential, with Xi Jinping’s state visit to the United States from September 23–25 potentially affecting tariffs, rare earths, and technology dynamics; a US–China accommodation preserving Chinese industrial access elsewhere could intensify European concerns about becoming a dumping ground for excess supply. The near-term choice lies between a negotiated form of managed interdependence and a more autonomous European effort to restrict, condition, and redirect selected Chinese trade and investment.