The latest analysis from Yahoo Finance pits Apple against ASML, asking which stock offers the stronger path into the coming year. The choice frames a contrast between consumer-facing scale and the hidden machinery driving the entire semiconductor industry.
Apple’s Integrated Ecosystem and Revenue Scale
Apple has built a consumer electronics empire that reaches into the pockets of billions. The company generates revenue by selling hardware such as the iPhone while steadily expanding its services segment. Indirect distribution channels, including third-party cellular network carriers and resellers, account for roughly 60% of total net sales. A licensing arrangement with Alphabet allows Apple to offer search services across its platforms, further diversifying its income streams.
In fiscal 2025, Apple reported revenue of nearly $416.2 billion, a growth of approximately 6.4% over the prior year. Net income reached close to $112 billion, yielding a net margin of 26.9%. The balance sheet as of September 2025 showed a debt-to-equity ratio of approximately 1.5 and a current ratio of 0.9, indicating that liabilities outpace liquid resources. Free cash flow for the year totalled roughly $98.8 billion.
ASML’s Lithography Monopoly and Semiconductor Demand
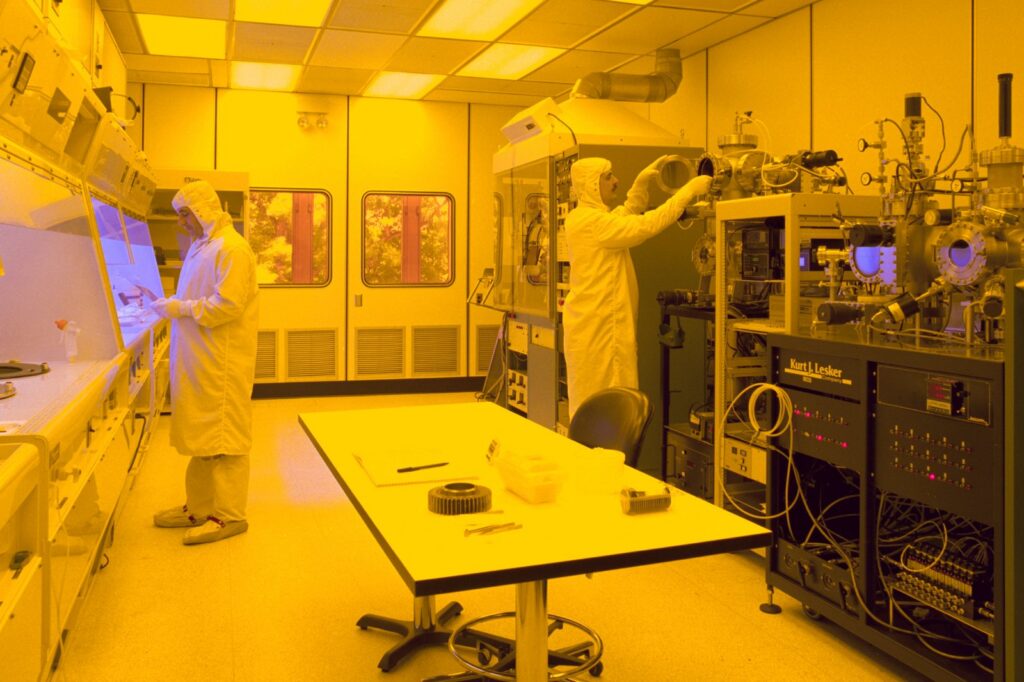
ASML occupies a uniquely critical position in the global technology supply chain. The company manufactures the lithography systems that enable chipmakers to print patterns onto silicon wafers. This equipment is vital for the production of advanced microchips used in everything from smartphones to artificial intelligence hardware. ASML operates as a primary supplier to global semiconductor manufacturers and maintains more than 60 locations worldwide.
In fiscal 2025, ASML reported revenue of nearly $36.8 billion, a 15.6% year-over-year increase. Net income reached $10.8 billion, resulting in a net margin of roughly 29.4%. The December 2025 balance sheet shows a debt-to-equity ratio of approximately 0.2 and a current ratio of nearly 1.3, indicating the company has sufficient liquid assets to cover upcoming liabilities. During the same period, ASML produced approximately $12.5 billion in free cash flow.
Comparing the Financial Profiles
When measured by scale, Apple dwarfs ASML. Apple’s fiscal 2025 revenue of $416.2 billion dwarfs ASML’s $36.8 billion, a reflection of the consumer device giant’s reach. However, ASML’s profitability metrics are slightly more efficient. ASML’s net margin of 29.4% exceeds Apple’s 26.9%, and its debt-to-equity ratio of 0.2 is substantially lower than Apple’s 1.5, suggesting a stronger balance sheet with less reliance on borrowed money. Free cash flow also favours Apple, which generated $98.8 billion compared with ASML’s $12.5 billion, a difference driven by the vastly different sizes of the two businesses.
Growth Trajectories and Sector Dynamics
Revenue growth rates tell a different story. ASML’s 15.6% year-over-year increase in fiscal 2025 outpaced Apple’s 6.4% growth, reflecting the accelerating demand for advanced lithography systems as chipmakers ramp production for artificial intelligence and other high-performance applications. Apple’s growth is constrained by the maturity of its core hardware markets and the cyclical nature of consumer spending, while ASML benefits from the structural expansion of the semiconductor industry, particularly as foundries invest in next-generation manufacturing nodes.
Both companies face distinct risks. Apple is subject to intense global competition in its primary hardware markets, which are characterised by aggressive pricing and rapid technological shifts. The company is also the subject of significant antitrust litigation, including an ongoing 2024 DOJ lawsuit regarding alleged monopolisation. A heavy reliance on single-source suppliers in Asia makes the business vulnerable to geopolitical tensions and trade restrictions.
ASML operates in the highly cyclical semiconductor industry, where shifts in demand can lead to volatile spending by chip manufacturers. Because its lithography machines represent a capital-intensive bottleneck, any slowdown in foundry investment directly impacts ASML’s order intake. The company’s geographic concentration in the Netherlands and its exposure to international export controls add further layers of complexity to its operating environment.
Geographic Exposure and Market Concentration
Apple’s revenue network spans the globe, but its operational footprint is heavily concentrated in Asia, particularly through manufacturing partnerships in China and Taiwan. This geographic reliance exposes the company to shifting trade policies and regional instability. In contrast, ASML’s operational base is anchored in the Netherlands, with a network of over 60 locations supporting its global customer base. While this European hub provides a stable regulatory environment, it also places ASML directly in the crosshairs of international export controls. The Dutch government has implemented strict licensing requirements for the shipment of ASML’s most advanced lithography systems, particularly those capable of producing chips at the 7-nanometer node and below. These restrictions, driven by geopolitical tensions between the United States and China, limit ASML’s ability to serve certain markets without government approval, creating a complex compliance landscape for the company’s international sales.
Furthermore, ASML’s customer base is intensely concentrated among a small number of foundries. The vast majority of the company’s revenue is derived from a handful of major semiconductor manufacturers, with TSMC representing a primary source of demand. This concentration means that any shift in foundry capital expenditure plans—whether driven by macroeconomic conditions or changes in technology roadmaps—has an outsized impact on ASML’s order intake. While Apple benefits from a diversified consumer base spanning hundreds of millions of device users, ASML’s financial performance is tightly coupled to the investment decisions of a few key players in the foundry sector, making its revenue stream more vulnerable to abrupt shifts in industry capacity planning.
Sources
- Apple vs. ASML: Which Tech Stock Is a Better Buy in 2026?
- AI boom
- Apple vs. ASML: Which Tech Stock Is a Better Buy in 2026? | The Motley Fool
Photo: Uploaded by Duk 08:45, 16 Feb 2005 (UTC) (Public domain)