The Market Moves on Cloud, Not Just Sentiment
REDMOND, October 29, 2026 — As technology stocks rallied ahead of earnings season, the broader market found its footing with Federal Reserve policy holding steady and consumer confidence figures surprising to the upside.
The rally was anchored by Microsoft Corporation, which delivered a first-quarter financial report that significantly exceeded Wall Street expectations. The company reported $92.3 billion in quarterly revenue, surpassing analyst estimates of approximately $90.6 billion. This performance confirms that demand for artificial intelligence and cloud computing services remains the primary driver of growth in the sector.
The technical reality behind these numbers shows a business model that has successfully transitioned from selling software licenses to providing essential infrastructure. Microsoft Corporation, an American multinational technology conglomerate headquartered in Redmond, Washington, has long dominated the operating system market with Windows and office suites like Microsoft 365. However, under the direction of CEO Satya Nadella, the company shifted its focus toward cloud computing and artificial intelligence starting in 2014.
This strategic pivot is evident in the latest financial figures released for the quarter ended September 30, 2026. Operating income rose to $45.9 billion, representing a 21% increase year-over-year. Net income climbed to $36.6 billion on a GAAP basis, marking a 32% increase. Diluted earnings per share reached $4.92, also up 32% compared to the prior period.
The core of this growth lies in the Microsoft Cloud segment, which generated $63.9 billion in revenue. Growth within this sector accelerated to 30% year-over-year, a figure that Amy Hood, executive vice president and chief financial officer of Microsoft, described as exceeding expectations across all key metrics. The commercial remaining performance obligation increased by 73% to $677 billion, indicating a deepening commitment from enterprise customers to multi-year cloud contracts.
Segment Performance Highlights Cloud and Productivity Strength
The breakdown of segment performance reveals where the capital is flowing most aggressively. Within the Microsoft Cloud business, commercial cloud revenue for Microsoft 365 increased by 18% on an adjusted basis. Consumer cloud revenue saw a similar boost with a 17% increase. Industry solutions cloud revenue grew by 10%, while Azure growth continued to support the overall enterprise stack.
In contrast, the Devices and Consumer segment saw a decrease in revenue of $3 billion, driven by specific product lines. XBOX content and services revenue decreased by 2%, and Windows OEM and Devices revenue fell by 22%. Despite this contraction in hardware sales, the company returned $10.2 billion to shareholders in the form of dividends and share repurchases during the first quarter of fiscal year 2027.
The technical underpinnings of these results involve significant investments in research and development. These releases are driven by years of R&D investment to empower customers with greater productivity, security, and differentiated value. The company also reported $15.5 billion in revenue for its Devices and Consumer segment, though the overall decline reflects a strategic shift away from hardware dependency toward recurring cloud services.
The impact on the broader tech rally is clear: investors are pricing in the success of this AI-driven cloud transition. The fact that Microsoft beat earnings estimates with $92.3 billion in revenue suggests that the market’s enthusiasm for tokenized stock trading and blockchain-based versions of the stock, as noted in recent filings, may be secondary to the fundamental strength of its core cloud infrastructure.
Looking forward, the company will provide guidance on its earnings conference call and webcast, offering further detail that matters for analysts tracking the sector. As ever, the market reaction to such reports depends less on the headline numbers and more on the trajectory of cloud adoption and AI integration. For now, the consensus remains that Microsoft’s shift toward cloud services has successfully insulated it from hardware cycles, providing a stable foundation for continued growth in an increasingly digital economy.
This report attributes all financial data to SEC filings and CoinGecko records retrieved on October 28, 2026. Sources include Gloria daily closes and company disclosures regarding fiscal periods ending September 30, 2026.
Shareholder Returns Amid Strategic Hardware Shift
Despite a notable contraction in its hardware division, Microsoft maintained a robust commitment to returning capital to investors. During the first quarter of fiscal year 2027, the company returned $10.2 billion to shareholders through dividends and share repurchases. This financial action occurred concurrently with a decline in revenue for the Devices and Consumer segment, which fell by $3 billion overall.
The specific drivers within this declining segment highlight a deliberate pivot away from reliance on physical hardware sales. XBOX content and services revenue decreased by 2%, while Windows OEM and Devices revenue saw a sharper drop of 22%. These figures reflect the broader corporate strategy established under CEO Satya Nadella, who took the helm in 2014 to shift focus toward cloud computing rather than traditional product cycles.
This transition marks a significant evolution from the company’s earlier history. Founded in 1975 by Bill Gates and Paul Allen, Microsoft initially rose to dominate the PC operating system market with MS-DOS in the mid-1980s, followed by Windows. While Steve Ballmer oversaw an increased focus on hardware leading to the Surface line in 2012, the current trajectory under Nadella emphasizes recurring cloud services over one-time hardware transactions. The company’s flagship products remain the Windows operating systems and the Microsoft Office suite, now evolving into the Microsoft 365 productivity applications.
The financial resilience demonstrated by these returns suggests that the market values the stability of its software and cloud infrastructure more than volatile hardware sales. As the enterprise stack continues to grow with Azure supporting industry solutions, the company’s ability to generate substantial operating income despite hardware headwinds underscores the success of this long-term strategic adjustment.
Sources
- Microsoft
- FY27 Q1 – Press Releases – Investor Relations – Microsoft
- Microsoft beats earnings estimates with $92.3B in revenue as it pushes back against tokenized stock trading
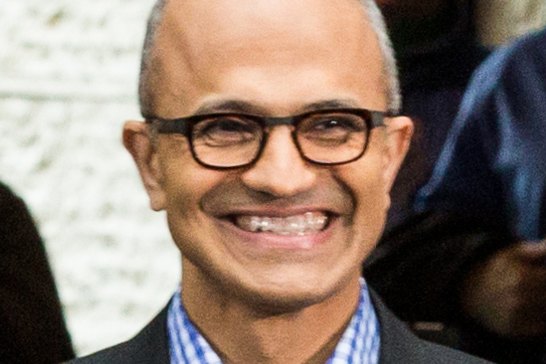
Photo: Briansmale (CC BY-SA 4.0)